Geopolitical risk remained central to markets during the third quarter, particularly developments in the Middle East. Disruption to energy flows through the Strait of Hormuz kept oil and gas markets under pressure and raised concerns about the reliability of other strategically-important trade routes.
Higher energy prices complicated the inflation outlook. Government bond yields rose across major developed markets as investors reassessed how quickly inflation might fall, and whether interest rates would need to remain higher for longer. Pressure was evident across the yield curve, reflecting a combination of changing policy expectations, inflation uncertainty and concerns about government borrowing.
Central bank expectations consequently became more hawkish, although the policy picture was not uniform. Rates remained unchanged in the UK over the period, while the US, Europe and Japan recorded increases. This divergence reflected the difficult balance between responding to energy-driven inflation and avoiding unnecessary damage to economic growth.
Economic activity nevertheless remained resilient. Leading indicators continued to suggest expansion across most major developed and emerging economies, while stronger energy prices accounted for much of the increase in headline inflation. Other components, including services inflation in the US and UK, remained comparatively contained during the period.
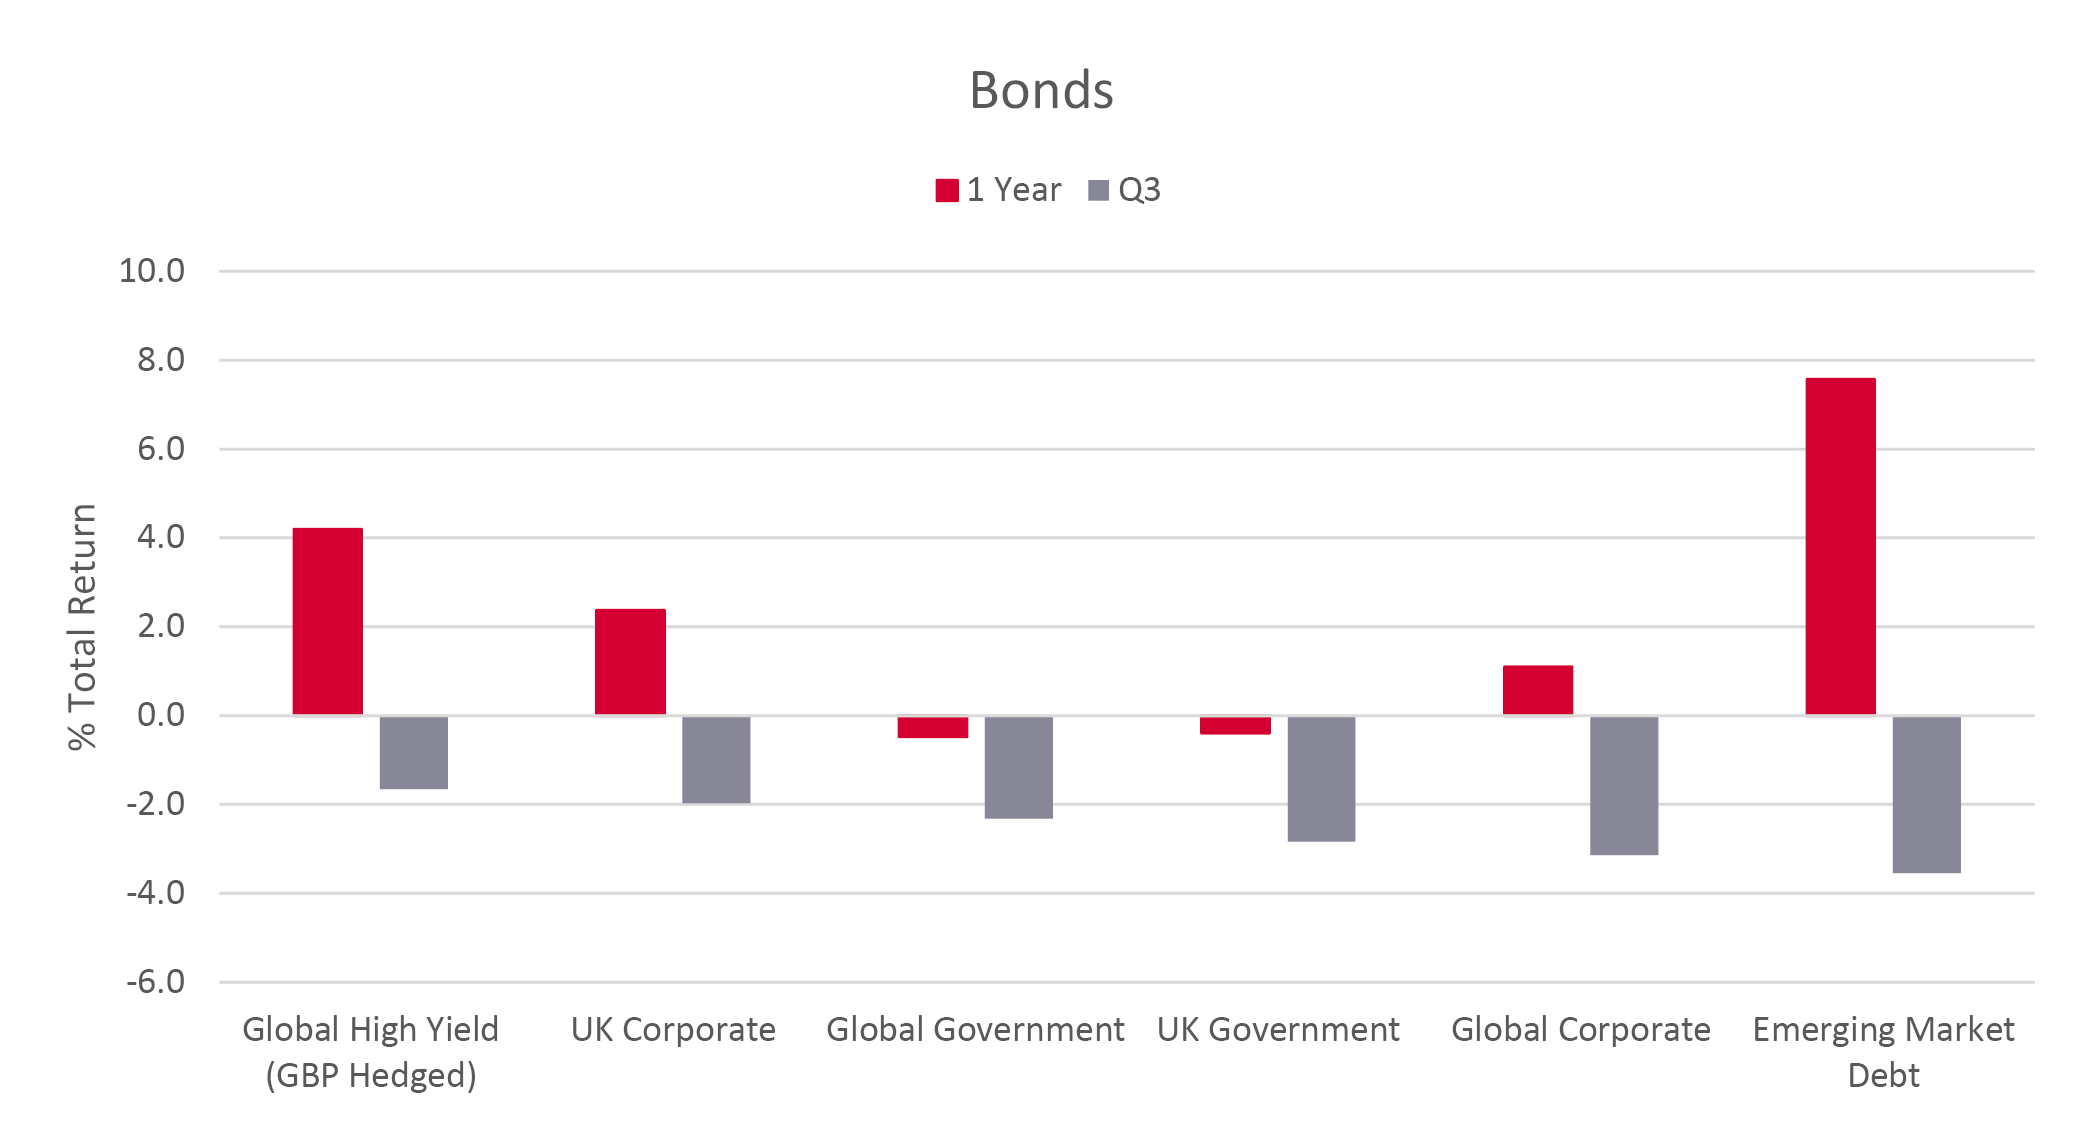
Source: AJ Bell and Morningstar, As of 30 September 2026. Total returns represent those in GBP terms.
Artificial intelligence also remained a major influence on equity markets, although leadership became less straightforward. Semiconductor and hardware companies experienced periods of volatility as investors reassessed valuations, capital expenditure and the durability of demand. Earnings remained supportive in many areas, but performance increasingly depended on where companies and markets sat within the AI supply chain.
This produced greater variation between regions and sectors rather than a simple divide between developed and emerging markets. Economies with substantial semiconductor exposure remained sensitive to shifts in AI sentiment, while energy companies benefited from stronger commodity prices. The quarter therefore underlined the limitations of relying on a single regional or thematic source of returns.
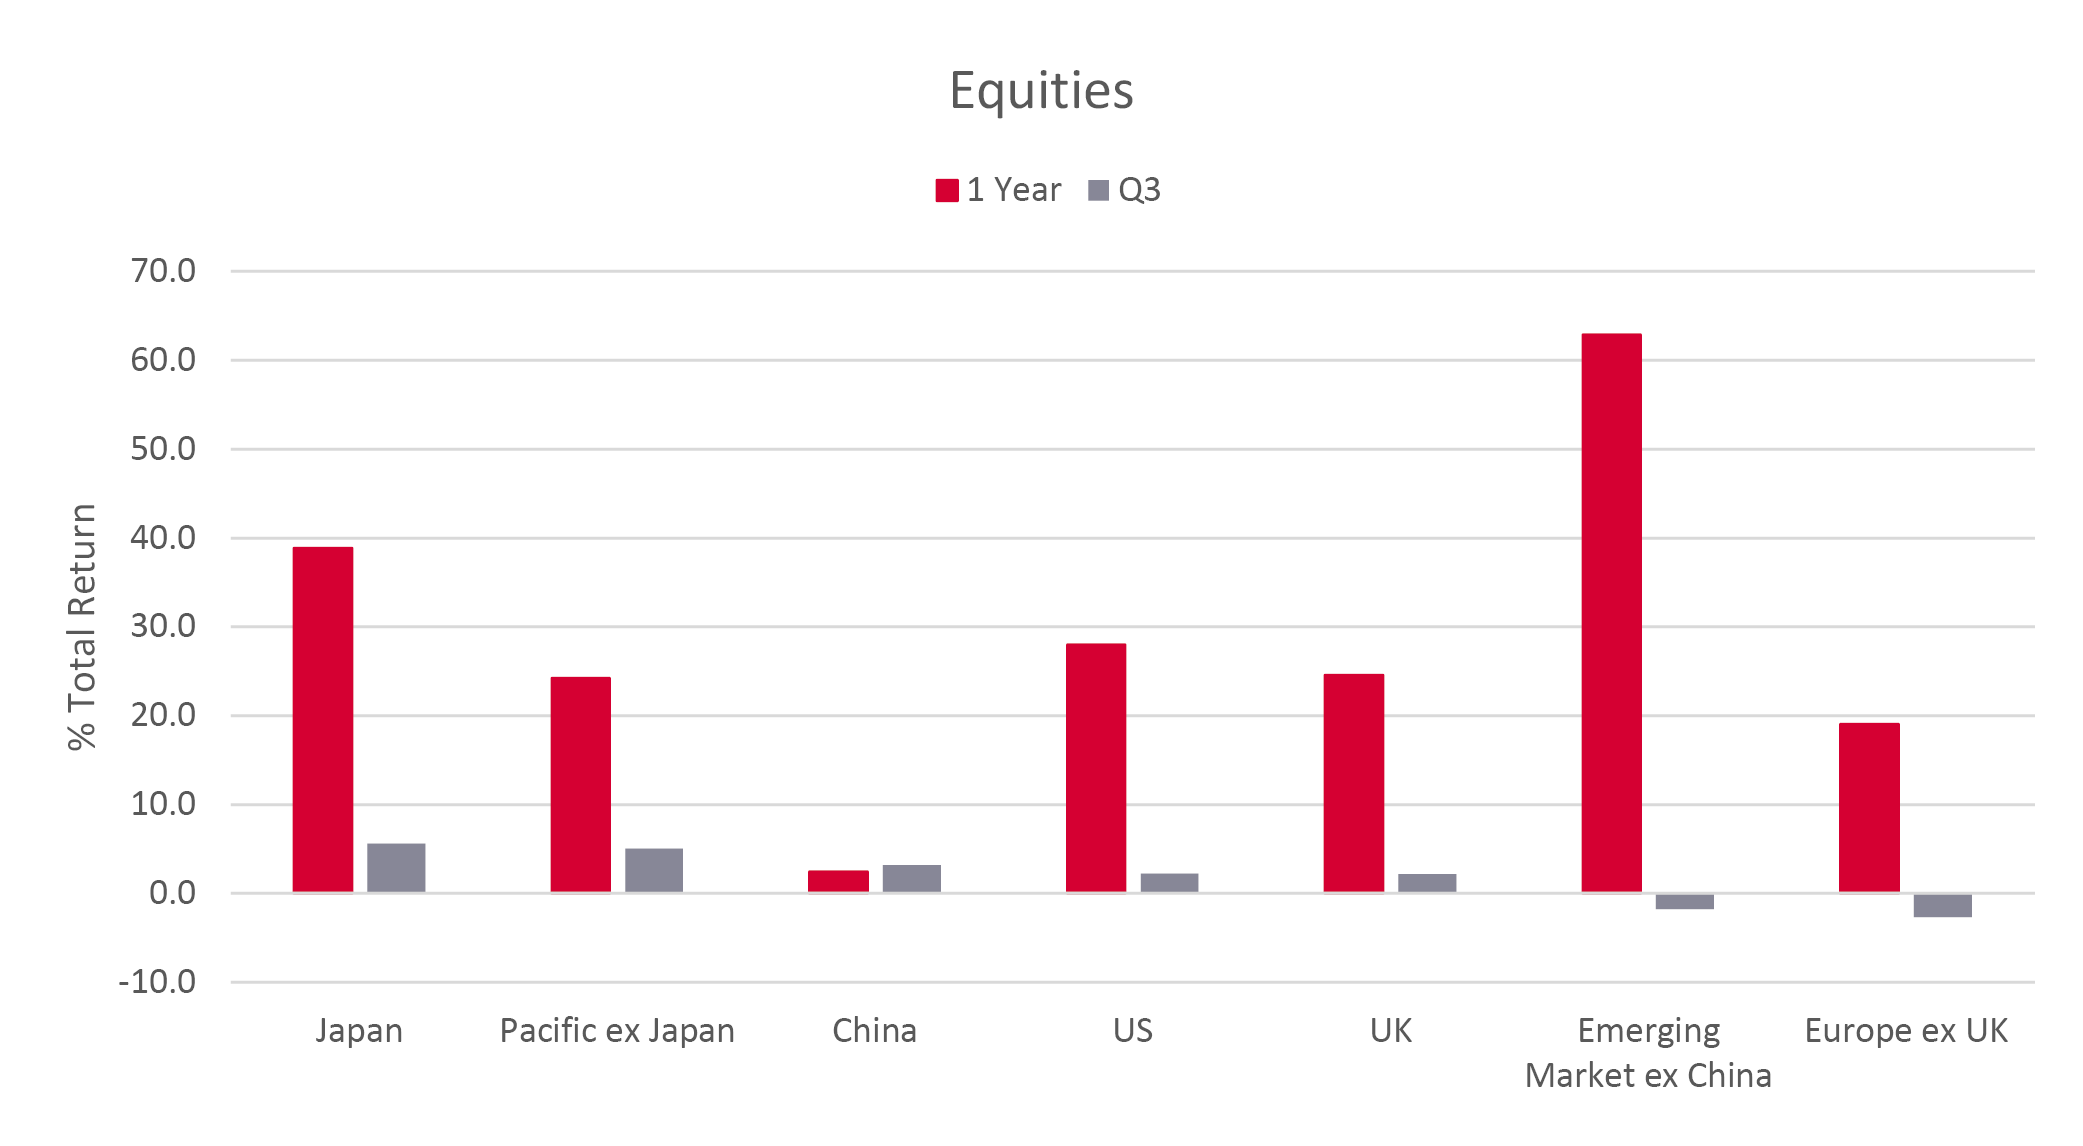
Source: AJ Bell and Morningstar, As of 30 September 2026. Total returns represent those in GBP terms.
Looking ahead, energy supply, inflation and monetary policy are likely to remain closely connected. Further disruption to critical shipping routes could place renewed pressure on prices and reduce the scope for central banks to ease policy. At the same time, resilient economic activity and company earnings provide support for risk assets.
The quarter reinforced the case for diversification across asset classes, regions and sectors. With interest rate expectations and equity market leadership capable of changing quickly, portfolios should be constructed for a range of outcomes rather than positioned around a single forecast.
Past performance is not a guide to future performance and some investments need to be held for the long term.


This article was written on 1 October
Many people choose to spread their investments around the world, but doing so effectively is often easier said than done.


This area of the website is intended for financial advisers and other financial professionals only. If you are a customer of AJ Bell Investcentre, please click ‘Go to the customer area’ below.
We will remember your preference, so you should only be asked to select the appropriate website once per device.